
Tax incentives have for many years been considered an essential tool for governments to attract foreign investment. However, if not carefully designed and monitored, they can drain government income and waste public resources, often without delivering the intended impact from the investment. These risks can be compounded by weak institutional coordination around key decisions: which government agency determines what incentives to offer and under what conditions, and who monitors whether they achieve their intended objectives?
Significant amounts are at stake. It is estimated that tax expenditures, provisions that reduce the tax liability of a person or business, lead to governments forgoing around 4% of global GDP and 24% of total tax revenue. Good governance is not simply about administering incentives efficiently. It requires that decisions to forgo public revenue are transparent, aligned with national priorities, and supported by evidence that the expected benefits justify their costs. Yet tax incentives sit at the intersection of tax and investment policy, and the institutions responsible for these areas do not always work together to achieve these goals.
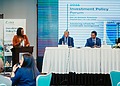
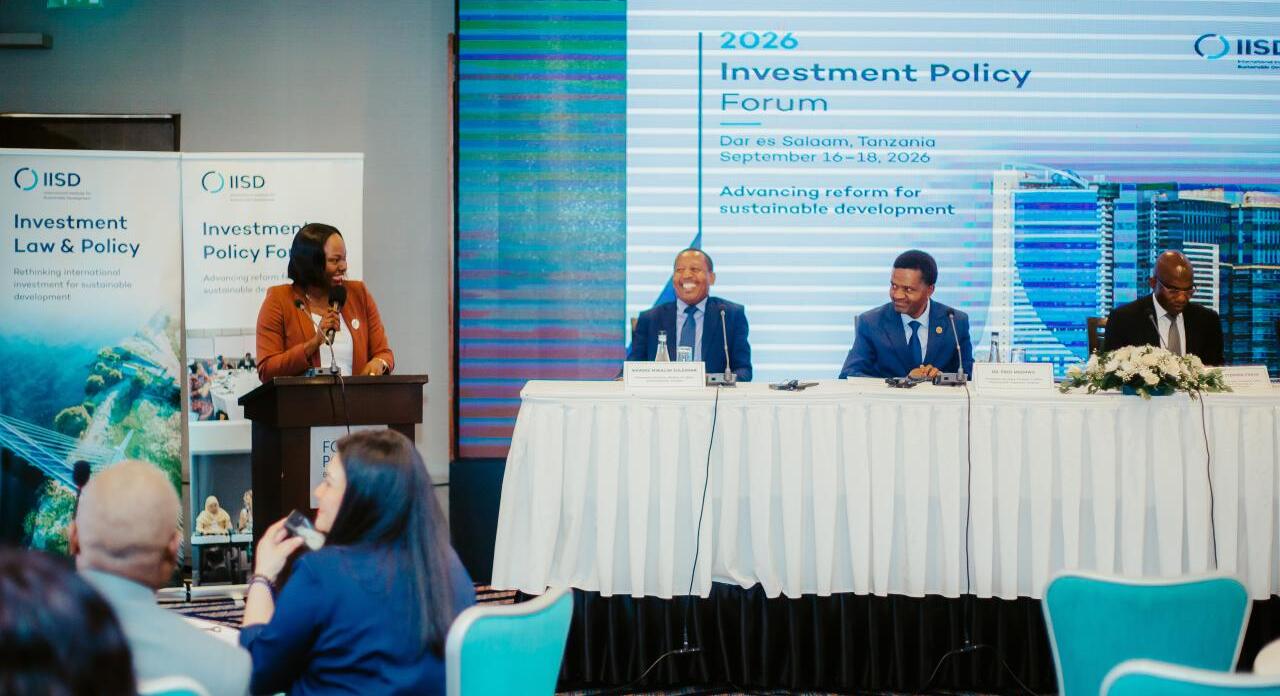
At the 2026 IISD Investment Policy Forum (IPF) held in Dar es Salaam, Tanzania, last month, we heard directly from policy-makers from emerging and developing economies about the barriers they encounter in governing incentives and successful approaches they have applied.
What makes coherent tax incentive governance difficult?
During our discussions at the IPF, investment policy-makers shared different challenges they have experienced that make tax incentive regimes difficult to govern coherently. One of the main challenges heard throughout conversations in Dar es Salaam was the fragmentation of mandates across government. Investment promotion agencies typically focus on attracting and facilitating investment, while ministries of finance are responsible for protecting the country’s tax base.
These different mandates translate into very different starting points: investment authorities may see incentives as an important tool to attract investors, while finance ministries may be reluctant to grant them at all.
These differences become more difficult to manage where there is no systematic review of existing incentives, no shared understanding of why a new incentive is needed, or no clear view of how much revenue the government is prepared to forgo. Participants stressed that better coordination requires more than seeking another agency’s approval once the main decisions have already been made. Officials need the technical capacity to understand each other’s mandates and a shared basis for determining when incentives are justified.
This institutional fragmentation is also often mirrored in the legal framework. As different government institutions are responsible for different aspects of investment and tax policy, incentives can end up spread across tax legislation, investment laws, special economic zone regimes, sectoral laws, and investment contracts. Participants highlighted the difficulties that arise when these different frameworks do not speak to each other. Incentives may overlap, investors may seek benefits under several regimes, and commitments made through one instrument can make another more difficult to reform.
Coordination is needed not only between institutions, but also across the different legal instruments through which incentives are granted.
Even where clear rules exist, political and investor pressure can create incentives (pun intended) to depart from them. Participants described cases where investors requested additional benefits, linking these requests to promises of significant investment without firm commitments. This can create pressure on governments to negotiate bespoke incentives outside the standard regime, particularly where authorities have broad discretionary powers to approve exceptions. Political pressure to demonstrate success in attracting investment can reinforce this dynamic. The challenge they found is how to limit the extent to which individual projects or political cycles can bypass the rules established for assessing the fiscal costs and expected benefits of incentives.
Lastly, policy-makers raised the difficulty of monitoring the cost and impact of incentives when relevant information is scattered across institutions. Assessing whether an incentive works requires different types of information: revenue authorities may hold data on its fiscal cost, while investment agencies may have information on the investment, jobs, or other commitments made by the beneficiary. Where these institutions do not systematically share information, or where no institution has a clear mandate to bring it together, governments struggle to determine the efficacy of incentives.
Weak monitoring can also create opportunities for abuse. Participants described cases where investors sought to continue benefiting from temporary incentives by changing their legal personality to re-enter a regime once a tax holiday had expired.
Related Articles
Here is a list of articles selected by our Editorial Board that have gained significant interest from the public:
How can governments strengthen tax incentives governance?
Our discussions at the IPF also provided insights into how countries are addressing these governance challenges. One approach is to establish clearer, rules-based access to incentives. When tax incentives and their eligibility criteria are defined in advance, investment and tax authorities have a common framework for deciding who can access an incentive. We heard from a country whose investment law no longer grants tax incentives directly, but instead links eligible investors to incentives established under tax legislation.
Setting clearer, rules-based access to incentives can help clarify institutional roles, limits discretion, and gives both government officials and investors greater certainty about the applicable rules.
Clear rules are particularly important when investors request incentives beyond the standard regime. Participants discussed approaches where exceptional incentives require additional justification for why the expected benefits warrant the additional cost. In some cases, these requests are also subject to parliamentary approval or other forms of external scrutiny. These additional steps can make decisions more transparent and accessible to the public, and reduce the risk of incentives being negotiated on a case-by-case basis behind closed doors. Participants also highlighted the role that parliaments and supreme audit institutions can play in overseeing incentive decisions, a function that is often underused.
Greater transparency over what incentives cost is a further building block. Many governments still do not know how much cash they miss out on through tax incentives. Participants highlighted the value of regular tax expenditure reporting that estimates the cost of each incentive and identifies its beneficiaries.
Producing these reports depends on several institutions within a government: finance ministries usually lead the estimates; revenue authorities hold the tax return data needed to calculate revenue forgone; investment promotion agencies and special economic zone authorities hold the records of which firms have been granted incentives. Where these institutions do not share information, reports are often incomplete.
Additionally, integrating tax expenditure reports into a country’s budget process allows parliaments and audit institutions to scrutinize incentives alongside direct spending. The Coalition on Tax Expenditures’ proposed Voluntary Minimum Standards for Tax Expenditure Reporting offer a practical reference point. They set out what credible reporting should cover, built around regularity, specificity, transparency, and integration with the budget.
But reporting costs is only a first step. Governments also need to assess whether incentives granted to investors actually delivered on their objectives and use that evidence to inform future decisions. This requires combining fiscal data with information held by investment agencies on investment, employment, or other commitments made by beneficiaries. It also requires sufficient technical capacity across institutions to analyze this information, and mechanisms to share it systematically.
Stronger coordination and internal expertise can help governments move from simply recording what incentives cost to deciding whether they are delivering their intended outcomes and whether they should be reformed.
How can we move from fragmentation to a shared approach?
The 2026 IPF reinforced that a coherent governmental approach to tax incentives is possible, even where responsibility remains spread across several institutions. This does not require one ministry to make every decision. It requires shared objectives, clearly defined responsibilities, and mechanisms through which institutions can exchange information and oversee incentives.
Finance ministries have an important coordinating role because decisions on tax incentives ultimately affect public revenue and need to remain aligned with national development priorities and fiscal objectives. But they cannot govern these regimes alone. Investment promotion agencies, revenue authorities, sectoral ministries, and other institutions all bring information and expertise needed to make better decisions.
Evidence can provide a common ground for decision making. Regular tax expenditure reporting, cost-benefit analysis, and evaluation can shift discussions away from competing institutional mandates toward a shared assessment of what incentives cost and what they deliver.
The insights gathered at the IPF will feed into IISD’s forthcoming work on the governance of tax incentives, including practical guidance on how governments can strengthen coordination across the full incentive policy cycle. They will also inform IISD’s work through the Coalition on Tax Expenditure Reform on minimum standards for tax expenditure reporting.
Ultimately, the question is not simply whether governments should not use tax incentives. It is whether they have the institutions, evidence, and rules needed to make those decisions in an informed, strategic, and coherent manner.
** **
This article was originally published by the International Institute for Sustainable Development (IISD) and is republished here as part of an editorial collaboration with the IISD. It was authored by Josefina del Rosario Lago and Kudzai Mataba.
Editor’s Note: The opinions expressed here by the authors are their own, not those of Impakter.com