
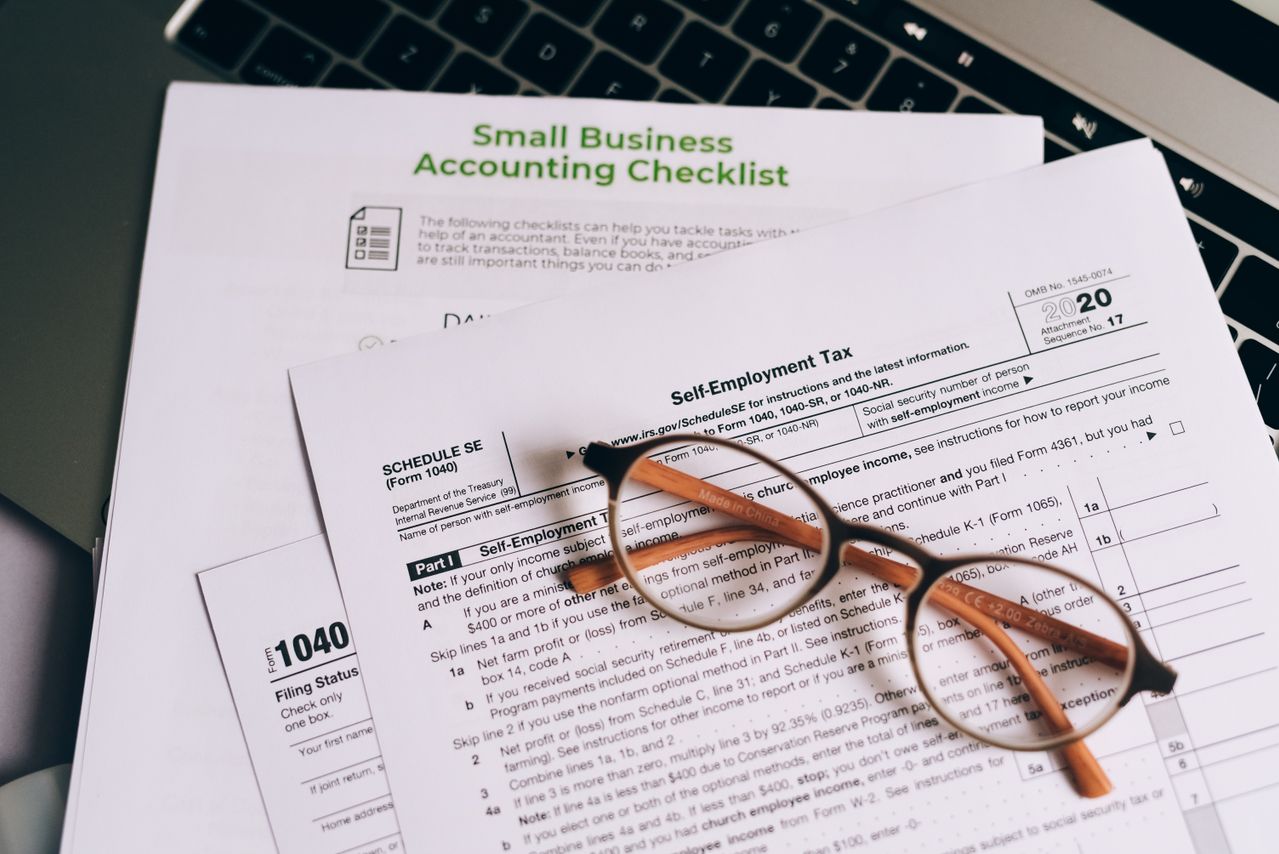
For returns filed in 2026, a partnership or S corporation that misses its deadline owes the IRS $255 per owner for each month the return is late, up to 12 months. A 4-partner firm that files 5 months late owes $5,100 in penalties before any tax is calculated. An extension requested on time moves that deadline back 6 months, and the IRS charges nothing to grant it.
Filing Deadlines by Business Structure
Partnerships and S corporations file first. Their 2025 returns were due March 16, 2026, since March 15 fell on a Sunday, and Form 7004 moved that date to September 15, 2026. C corporations follow the individual calendar, so a calendar-year C corporation’s 2025 return was due April 15, 2026, and an extension moved it to October 15, 2026.
Sole proprietors and single-member LLCs that have not elected corporate treatment report business income on Schedule C of the owner’s Form 1040. Their deadline is the personal deadline, and their extension is the personal extension. The same timeline governs partners and S corporation shareholders who receive Schedule K-1 forms, because the income on those forms ends up on each owner’s individual return.
Form Selection for Each Entity Type
Form 7004 and Form 4868 apply to nearly every small business. Form 7004 extends the returns of partnerships, corporations, and most trusts and estates. Form 4868 extends Form 1040, which includes any Schedule C income.
Form 7004 asks for the business name, the employer identification number, a code for the return type, and an estimate of the tax due. The IRS does not ask for a reason, and approval is automatic when the form is submitted by the original due date. Selecting the wrong return code attaches the extension to a return the business does not file, which leaves the actual return unextended.
Electronic submission produces an acceptance or rejection notice from the IRS. That notice belongs with the business records, since it shows the request arrived before the deadline. A paper Form 7004 sent by certified mail provides the same proof through the postmark and the mailing receipt.
An owner of an S corporation or partnership often needs both forms. The entity files Form 7004 by March, and each owner who cannot complete a personal return without the final K-1 files Form 4868 by April 15. The personal return cannot be completed until the business numbers are final, and a partnership that extends to September can leave its partners waiting on K-1 figures well past April. The FileTax tax extension guide assigns Form 4868 to people filing their own returns, including the self-employed, and Form 7004 to partnerships, corporations, certain LLCs, trusts and estates.
Payment Obligations During an Extension
Neither form changes when tax is due. A C corporation that expected to owe for 2025 had to pay its estimated balance by April 15, 2026, and interest began on any unpaid amount from that date. Sole proprietors are in the same position on the personal return. Form 7004 has lines for the tentative total tax, the payments already made, and the balance due, and that balance can be paid at the same time the request is submitted.
For individual taxpayers, IRS interest rates on underpayments equal the federal short-term rate plus 3 percentage points, compounded daily, and the rate was 7% for the final quarter of 2026. The IRS resets it each quarter, and it was 6% from April through June, so a balance left unpaid from April to October grows a little every day of those 6 months.
Partnerships and S corporations are pass-through entities that generally pay no income tax at the entity level, so their extension is mostly a matter of paperwork. Their owners still owe tax on their shares of the profit, and those amounts are due on the personal timeline.
Penalties After a Missed Deadline
A valid extension resets the starting point for late-filing penalties. A partnership or S corporation that misses September 15 by 1 week owes 1 month of the per-owner penalty, since any part of a month counts as a full month, while a business that never requested an extension and files on the same day owes 7 months for every owner on the books.
For returns that show tax owed, the failure-to-file penalty is 5% of the unpaid tax for each month or part of a month, capped at 25%. The failure-to-pay penalty is 0.5% per month, with the same 25% cap. When the 2 penalties apply in the same month, the filing penalty is reduced by the payment penalty, so the combined charge is 5%. A sole proprietor who owes $8,000 and files and pays 2 months late with no extension owes $800 in combined penalties plus interest. With an extension in place and the same late payment, the penalty is $80. For returns due in 2026, a return more than 60 days late is also subject to a minimum penalty of $525 or 100% of the unpaid tax, whichever is smaller.
The IRS offers first-time penalty abatement to taxpayers who had no penalties in the 3 prior tax years, apart from estimated tax penalties, and it can remove penalties for reasonable cause, such as a serious illness or a natural disaster. Interest is not removed by either form of relief.
State and Local Requirements
A federal extension does not automatically extend a state return. Some states accept the federal extension in place of their own form, and others require a separate request, often with a payment of the estimated balance. California gives corporations in good standing an automatic 7-month extension with no form, although payment is still due on the original date. New York requires corporations to submit Form CT-5 and pay the estimated franchise tax by the original due date, and S corporations use a separate version, Form CT-5.4.
Several cities tax business income directly as well. New York City and many Ohio municipalities impose their own business taxes, and their deadlines and extension rules are separate from the state’s.
Estimated Payments and Payroll Deadlines
An income tax extension applies to 1 annual return. It has no effect on quarterly estimated payments for the current year, which for calendar-year owners are due April 15, June 15, September 15 and January 15. Corporations that owe estimated tax follow a similar quarterly pattern, with the fourth installment due December 15 for calendar-year companies. An owner avoids the estimated tax penalty by paying at least 90% of the current year’s tax or 100% of the prior year’s tax through the 4 installments, and the prior-year figure rises to 110% when adjusted gross income was above $150,000.
Payroll obligations are also unaffected. Deposits of withheld payroll taxes follow the employer’s deposit schedule, and Forms W-2 and 1099-NEC are due January 31, or the next business day when that date falls on a weekend, to both the recipients and the government. An owner who extends the business return in March still has to meet every payroll date in the months that follow.
Calendar Dates for the 2026 Returns
For 2026 returns, partnerships and S corporations are due March 15, 2027, and C corporations and sole proprietors are due April 15, 2027. An owner who writes the correct date and form number on the calendar now, with a reminder 2 weeks earlier to estimate the balance owed, has taken the step that prevents the per-owner penalty and limits interest to whatever is still unpaid on the original due date.
Editor’s Note: The opinions expressed here by the authors are their own, not those of impakter.com — In the Cover Photo: Small business tax extension planning starts with checking filing deadlines, estimated tax and business records. — Cover Photo Credit: Leeloo The First