
Today’s ESG Updates
- MSC and BlackRock Withdraw Barcelona Port Bid: The companies pulled their EU approval request after regulators raised concerns the deal could raise prices and disadvantage rival shipping firms.
- JBS Names Wesley Batista Filho as CEO: The world’s largest meatpacker named Wesley Batista Filho as chief executive effective in 2027, replacing Gilberto Tomazoni, who has led the company since 2018.
- Blackstone’s Safe Harbor Nears $1.5 Billion Deal for MarineMax: The marina operator’s acquisition of the yacht retailer caps a months-long bidding war involving Donerail and Centerbridge.
- Oil Leak Near Oman Nature Reserve Spreads to Nearly 400 Sq Km: A sanctioned Russian “shadow fleet” tanker grounded off the Hallaniyat Islands is leaking oil into a protected marine habitat.
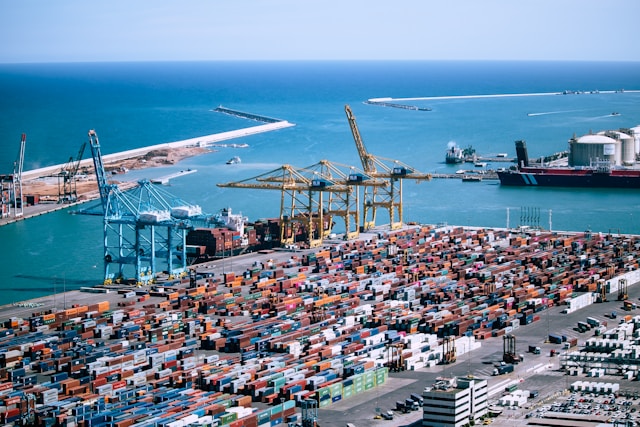
MSC and Blackrock withdraw bid for Barcelona port terminal
Shipping giant MSC and buyout fund BlackRock have withdrawn their request for EU antitrust approval to buy CK Hutchison’s Barcelona port terminal, a regulatory filing has shown. The European Commission had opened a full-scale investigation last December over concerns the deal could raise prices or lower the quality of container terminal services.
Under the proposed deal, MSC’s Terminal Investment Limited Holding (TiL) and BlackRock would have jointly controlled the terminal, which is the main deep-sea gateway for cargo to and from Barcelona and southern Europe. The EU had warned the merged entity could disadvantage rival shipping companies while giving MSC preferential treatment. BlackRock, MSC and CK Hutchison did not immediately respond to requests for comment.
Klimado – Navigating climate complexity just got easier. Klimado offers a user-friendly platform for tracking local and global environmental shifts, making it an essential tool for climate-aware individuals and organizations.
JBS names Wesley Batista Filho as CEO, returning founding family to helm
JBS, the world’s largest meatpacker, named Wesley Batista Filho as chief executive effective January 2027, the Brazilian company said Monday; its first CEO change in eight years and a return of the founding Batista family to the group’s top operating role. Batista Filho, 34, currently head of JBS USA, will replace Gilberto Tomazoni, who has led the company since 2018 and will move to vice chairman and senior adviser. U.S.-listed JBS shares fell about 5.5% on the news.
Batista Filho, son of Wesley Batista, who with brother Joesley Batista controls JBS’s holding company J&F, joined JBS in 2011 and has held senior roles across its beef and poultry operations in Brazil, Uruguay, Paraguay and Canada before taking over JBS USA in 2023. “This is a transition defined by continuity,” he told Reuters, adding the shift should be straightforward given his experience within the company. He said JBS would focus on expanding in the Middle East, Southeast Asia and Oceania, building on a deal in Indonesia last week, while investing in higher-value products and growing its egg and fish businesses.
The last Batista family member to run JBS was founder Jose Batista Sobrinho, father of Wesley and Joesley, who was replaced by Tomazoni in 2018 after the brothers stepped back amid a corruption scandal; both were arrested over insider trading allegations tied to a sealed plea agreement and later acquitted, returning to JBS’s board in 2024.
Related Articles
Here is a list of articles selected by our Editorial Board that have gained significant interest from the public:
Blackstone’s Safe Harbor nears $1.5 billion deal for MarineMax
Blackstone Infrastructure’s Safe Harbor Marinas, the world’s largest marina owner and operator, is nearing a $1.5 billion deal to acquire yacht retailer MarineMax, people familiar with the matter told Reuters. The agreement would cap a months-long bidding battle that also included activist investor Donerail and private equity firm Centerbridge, with Safe Harbor set to pay around $53 per share in cash, which is a significant premium to MarineMax’s Friday close of $35.68, valuing its equity at roughly $1.17 billion.
MarineMax operates 65 marinas and storage locations and 70 dealerships, mostly in the U.S., catering to a wealthy clientele, and held $335 million in long-term debt as of end-June. A deal could be announced as soon as this week barring last-minute complications, sources said. It would be Safe Harbor’s most significant deal since Blackstone acquired it in a $5.7 billion buyout last April, and would expand its marina network across the U.S., Caribbean and Mediterranean. Donerail had pushed MarineMax since October to sell itself or replace CEO Brett McGill, in a bidding war that reflects growing investor appetite for the marina business as lower interest rates support high-end consumer spending on luxury items like yachts. MarineMax did not immediately respond to a request for comment; Blackstone declined to comment.

Oil leak near Oman nature reserve spreads to nearly 400 sq km
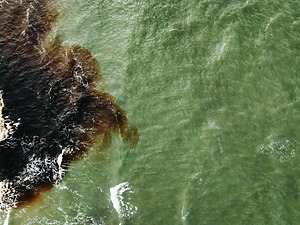
A tanker grounded off a nature reserve in Oman has leaked oil covering nearly 400 square kilometres, the government said Monday. The Caroline Bezengi, carrying close to one million barrels of Russian oil, first reported trouble off Yemen on June 8, with sources pointing to a possible onboard blast; no one has claimed responsibility.
Oman said the slick, near the Hallaniyat Islands nature reserve, extends to within about seven kilometres of the coast, with no threat yet to nearby facilities — though Greenpeace put the size closer to 600 square kilometres last week. Experts warn that if oil reaches shallow coastal waters, the damage to marine life could persist for years, as it did after the 1989 Exxon Valdez spill. Built in 2001, the tanker is part of Russia’s sanctioned “shadow fleet” of uninsured vessels that obscure ownership; its owner and manager, both apparently China-based, could not be reached.
Editor’s Note: The opinions expressed here by the authors are their own, not those of impakter.com — Cover Photo Credit: Ogla Subach