
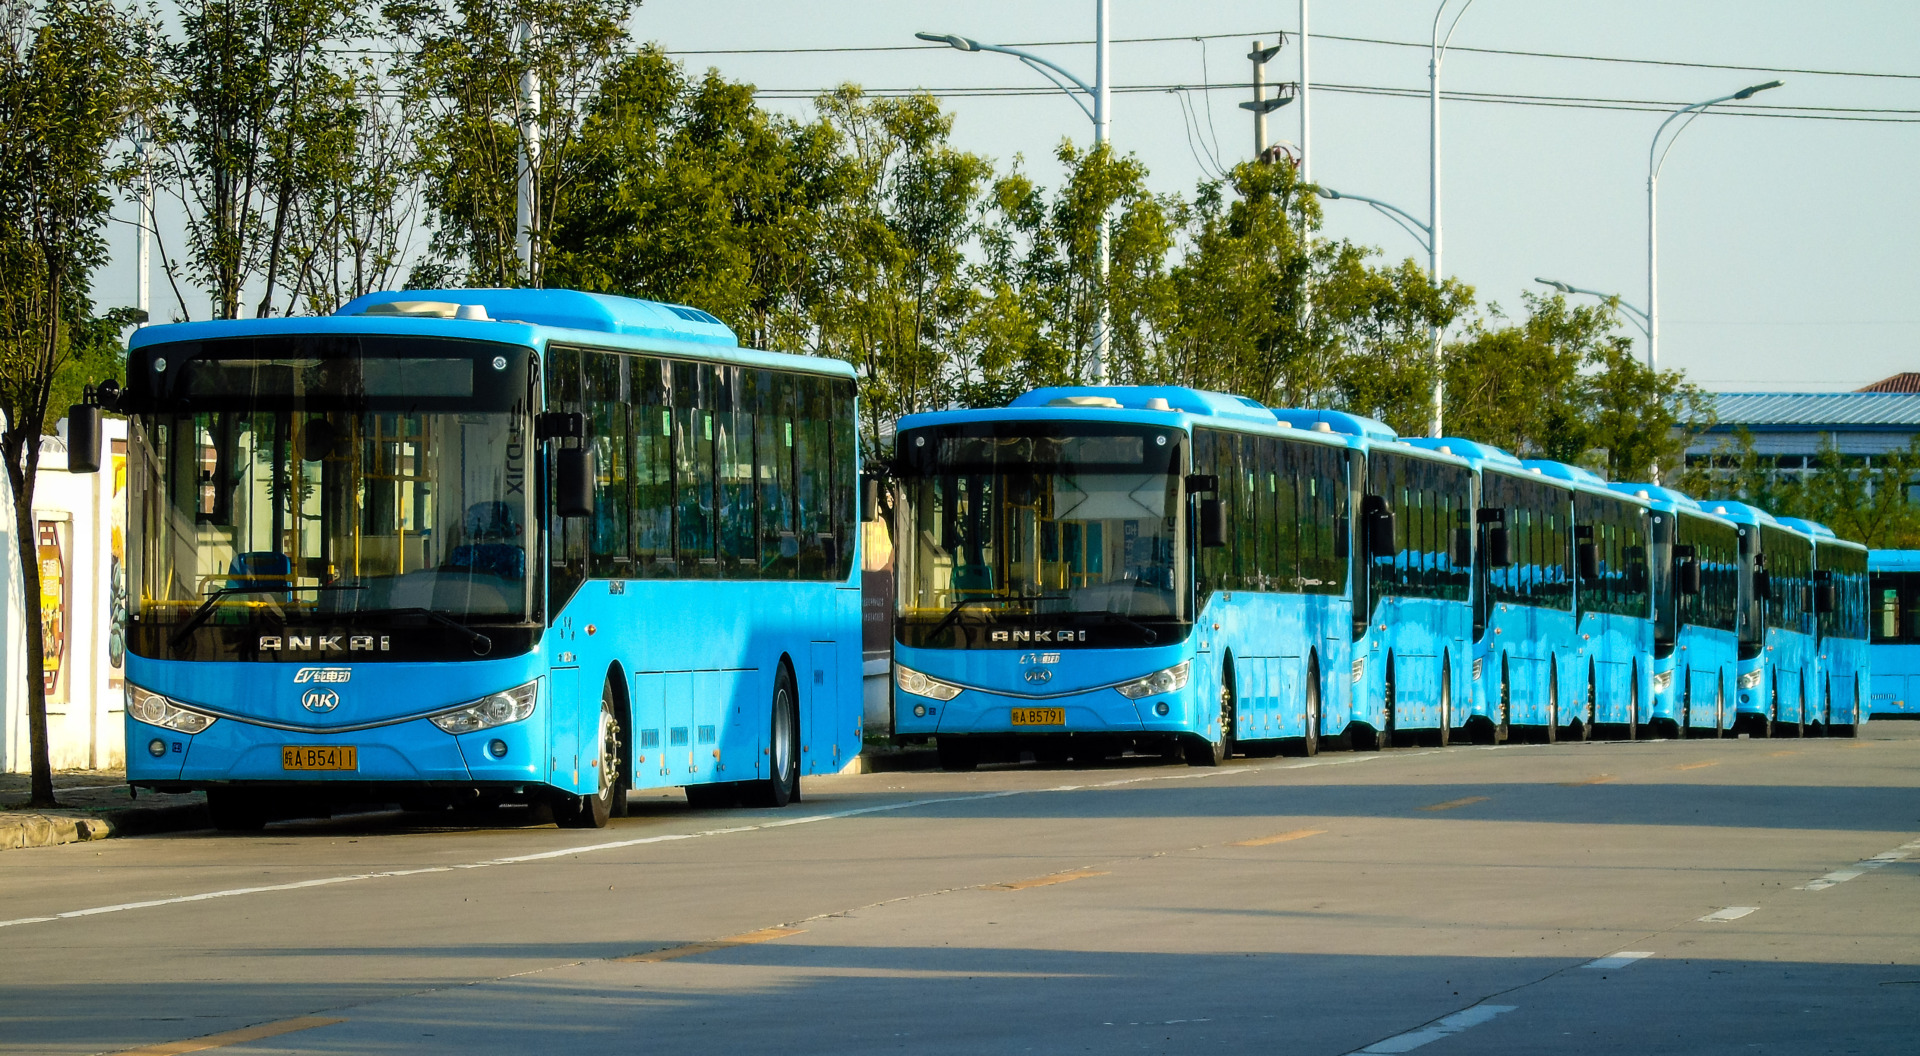
At least seven of the 21 BRICS+ economies are directing subsidies toward electric vehicles (EVs) and transport services widely used by lower- and middle-income people — from two- and three-wheelers to buses and shared transport. EVs are often portrayed as products for affluent households. Yet some BRICS+ economies direct support to electric two- and three-wheelers (E2Ws and E3Ws), buses, and shared transport, widely used by two-wheeler riders, auto-rickshaw drivers, delivery workers and bus passengers. These groups are less likely to benefit from private-car subsidies, even though the modes they rely on account for a significant share of everyday mobility in many emerging economies.
Transport electrification can therefore offer more than climate benefits: depending on policy design, it can reduce exposure to volatile fossil fuel costs and make cleaner mobility more accessible to a broader section of the population.
This story examines how selected BRICS+ economies are extending EV support to lower- and middle-income users, how this has improved affordable transport, and what other emerging economies can learn. Two approaches stand out: supporting relatively affordable vehicles and electrifying public and shared transport.
About BRICS+ and the Scope of This Story
BRICS+ brings together 11 member countries — Brazil, China, Egypt, Ethiopia, India, Indonesia, Iran, Russia, Saudi Arabia, South Africa, and the United Arab Emirates — and 10 partner countries: Belarus, Bolivia, Cuba, Kazakhstan, Malaysia, Nigeria, Thailand, Uganda, Uzbekistan, and Viet Nam.
This review identifies at least seven economies — Brazil, China, Ethiopia, India, Indonesia, Malaysia, and Thailand — with concrete policies that direct EV support toward lower-cost personal vehicles or public and shared transport used by lower- and middle-income people.
We assess policies that directly shape EV uptake and access, including purchase support, public procurement, finance, and selected regulatory measures. Manufacturing, trade, and wider infrastructure policies are generally outside the scope of this story, although they also affect EV costs and availability.
Note: Even though the subsidy allocation figures were available in local country-specific currencies, we only report USD figures, targeted at the global audience. Exchange rates were sourced from https://www.exchangerates.org.uk/, and the average of the available daily rates from January 2026 to August 13, 2026 was used for each respective currency.
Why Inclusive EV Policy Matters Now
Around 80% of the world’s population lives in countries that are net oil importers. This figure is even higher across BRICS+, where 14 of 21 economies, accounting for around 84% of the group’s population, are net importers of crude oil and petroleum products (see figure below). This dependence leaves households and governments exposed to international oil price volatility, which can raise transport costs and wider inflationary pressures. Even some net crude-oil exporters remain exposed if they import fuel products or price them at international rates.
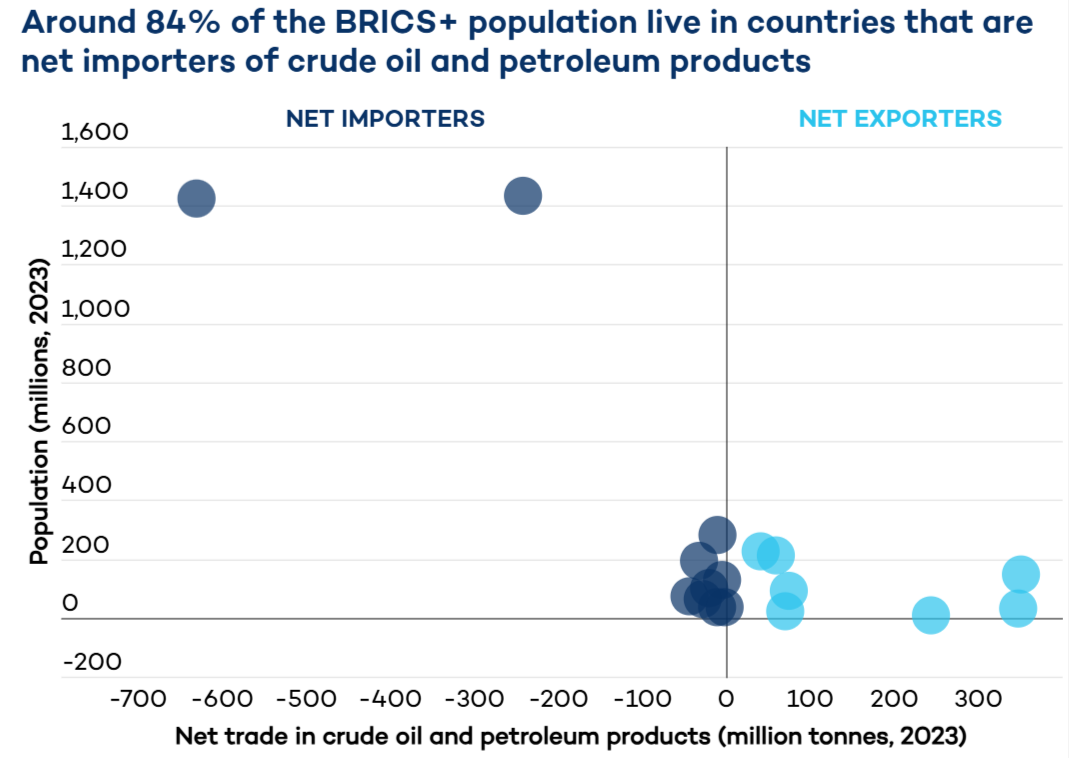
Note: Net trade combines each economy’s net trade balance for crude oil and petroleum products, expressed in million tonnes; negative values indicate net-importing economies, and positive values indicate net-exporting economies. The 84% figure is calculated as the share of total BRICS+ population living in economies with a negative combined trade balance. Other BRICS+ countries in the chart include Uganda, Cuba, Bolivia, Belarus, and Egypt.
The 2026 Strait of Hormuz disruption brought this exposure into focus. Around a quarter of global seaborne oil trade passed through the strait in 2025, with China and India together receiving 44% of the crude oil flowing through it. The disruption sharply reduced flows and drove renewed oil-market volatility.
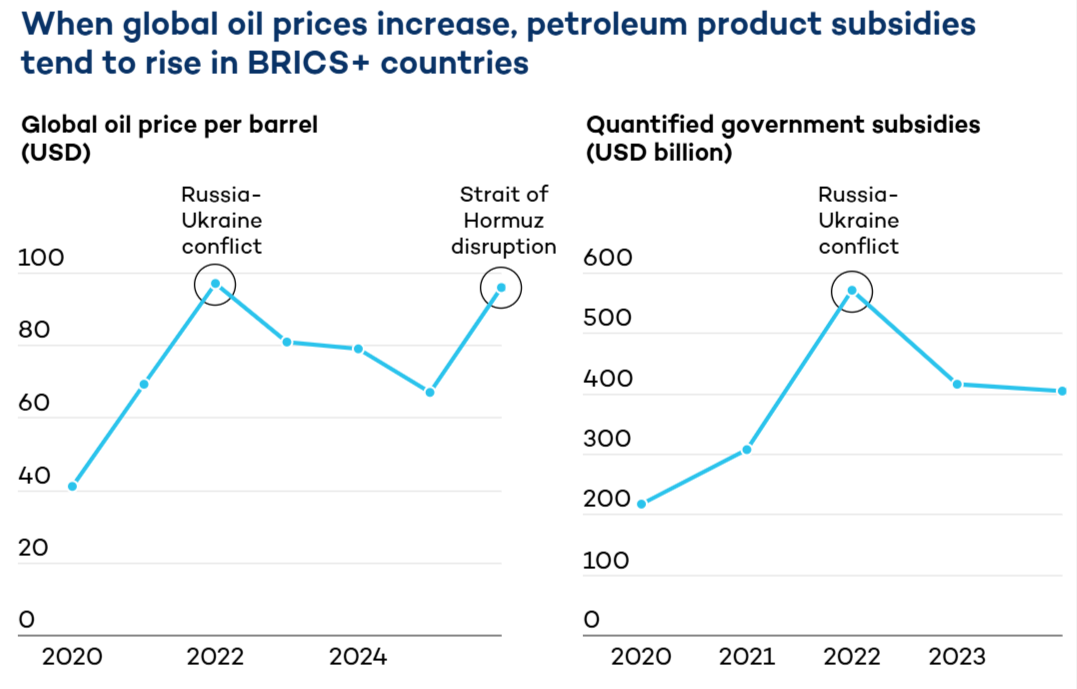
Oil price shocks can also create fiscal pressures when governments intervene to cushion consumers. The figure below shows that petroleum product subsidies across BRICS+ have tended to rise during periods of high global oil prices. By artificially reducing prices for consumers, consumption subsidies for petroleum products also erode the economic case for clean alternatives. Comparable subsidy data are available only through 2024, so the figure does not yet capture responses to the 2026 disruption.
Road transport accounts for around 45% of global oil demand, making electrification an important route to reducing oil dependence. Globally, EVs displaced ~1.7 million barrels per day (mbpd) of oil in 2025, roughly Indonesia’s daily consumption, and this is projected to approach 5 mbpd by 2030. Falling battery costs and growing competition are making EVs more affordable. Governments can accelerate uptake through subsidies, public procurement, regulation, and enabling infrastructure — but how these tools are targeted determines who benefits.
Many early large-scale EV incentive programs are centred on electric passenger cars. Because car ownership and new-vehicle purchases are concentrated among higher-income households, these policies have often directed more public support toward better-off consumers.
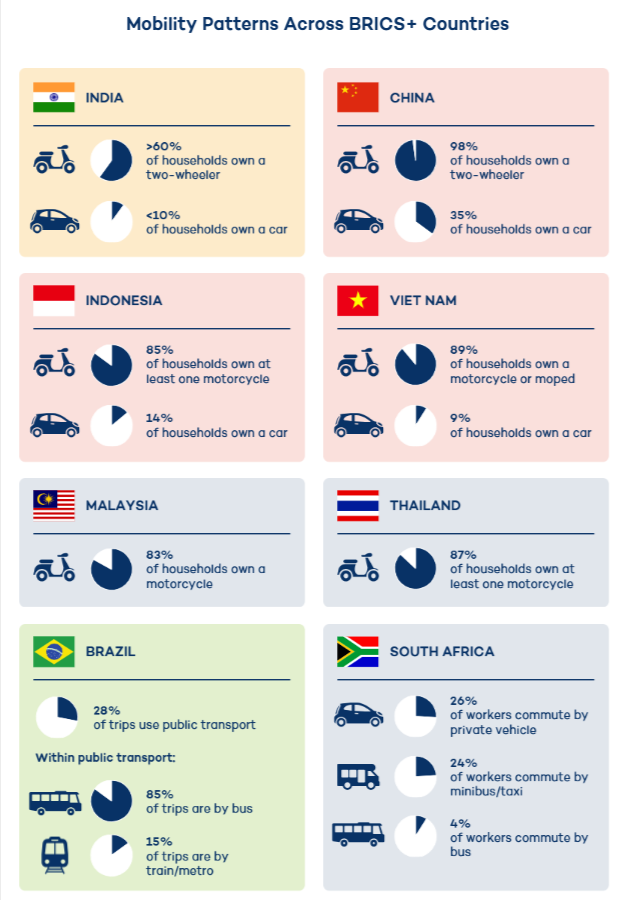
Some BRICS+ economies are taking a different approach by directing support toward motorcycles, scooters, auto-rickshaws, buses, and shared transport — modes widely used by lower- and middle-income people. Governments do this by lowering vehicle costs, setting income or vehicle-price limits, supporting commercial and public transport, and sometimes requiring new vehicles in selected categories to shift to electric. EV policy can therefore support energy security and cleaner transport while extending benefits to a broader section of the population.
Putting the Principle Into Practice
Countries apply inclusive EV policy differently, depending on their transport systems, vehicle ownership and available resources. Across BRICS+, two broad pathways emerge:
- Support relatively affordable vehicles used widely by lower- and middle-income people, particularly motorcycles, scooters, and electric bicycles.
- Electrify public and shared transport, including buses, three-wheelers, and minibuses that provide mobility regardless of vehicle ownership.
Affordability matters in both pathways, but financing needs differ. Individual buyers may need purchase or credit support, while cities and commercial operators may need to spread higher upfront costs out over time.
Pathway 1: Support Widely Used, Lower-Cost Vehicles
In several BRICS+ economies, motorcycles, scooters, and e-bicycles provide relatively affordable mobility for lower- and middle-income households and workers. Governments support their electrification through purchase incentives, price limits, trade-ins, conversion subsidies, and, in some cases, income-based eligibility, all aimed at lowering the financial barrier to switching.
Why Two-Wheelers Matter for Inclusive EV Policy in BRICS+
Where income-level evidence is available, it strengthens the inclusion case
India: How India Adapted Support as the E2W Market Grew
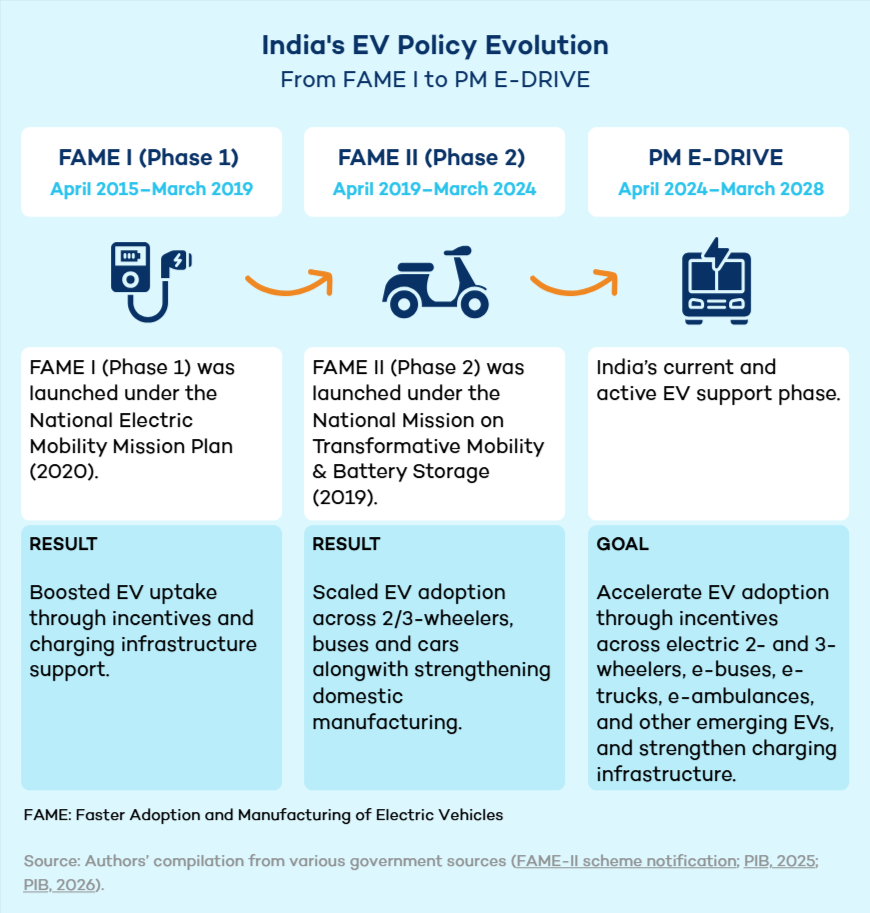
India’s EV support developed in stages. The National Electric Mobility Mission Plan 2020, launched in 2013, set out a vision for accelerating EV adoption. The first round of Faster Adoption and Manufacturing of (Hybrid &) Electric Vehicles in India (FAME-I; 2015–2019) was launched next, providing direct purchase support. For E2Ws, FAME-I offered upfront purchase subsidies of USD 79–308 per vehicle, depending on battery technology and performance. Over 151,000 E2Ws were supported under FAME-I, well over half of the 255,305 EVs supported across all vehicle categories.
As the market gained momentum, India strengthened that support. FAME-II (2019–2024) introduced a more standardized, battery-capacity-based subsidy. When launched in 2019, the E2W subsidy was USD 106 per kWh of battery capacity, capped at 20% of vehicle cost, which was increased to USD 160 per kWh in June 2021 (capped at 40% of vehicle cost). E2W uptake subsequently increased from 0.4% of all two-wheeler sales in the first half of 2021 to 7.1% by May 2023.
As adoption expanded, India began to recalibrate its support. The ongoing EV scheme, PM Electric Drive Revolution in Innovative Vehicle Enhancement (PM E-DRIVE; 2024–2028), continues to support E2Ws, with the subsidy moving from USD 53 per kWh in its first year to USD 26.5 per kWh from April 2025, subject to a maximum of USD 53 per vehicle and 15% of the vehicle’s cost, whichever is lower. Support is capped at 4.58 million E2Ws, with USD 293 million allocated to the segment.
This phased approach has supported continued market growth: E2W penetration reached 10.6% by June 2026 and a record 11.2% by July 2026. By early August 2026, around 2.37 million E2Ws had been registered under PM E-DRIVE.
 India’s central support is increasingly complemented by state policy. States can add purchase incentives, tax benefits, or regulations to reflect local market conditions. Delhi’s 2026 EV policy illustrates this layered approach: alongside central PM E-DRIVE support, the city provides additional incentives for E2Ws and requires all newly registered two-wheelers to be electric as of April 2028.
Indonesia: Why Continuity of Support Matters
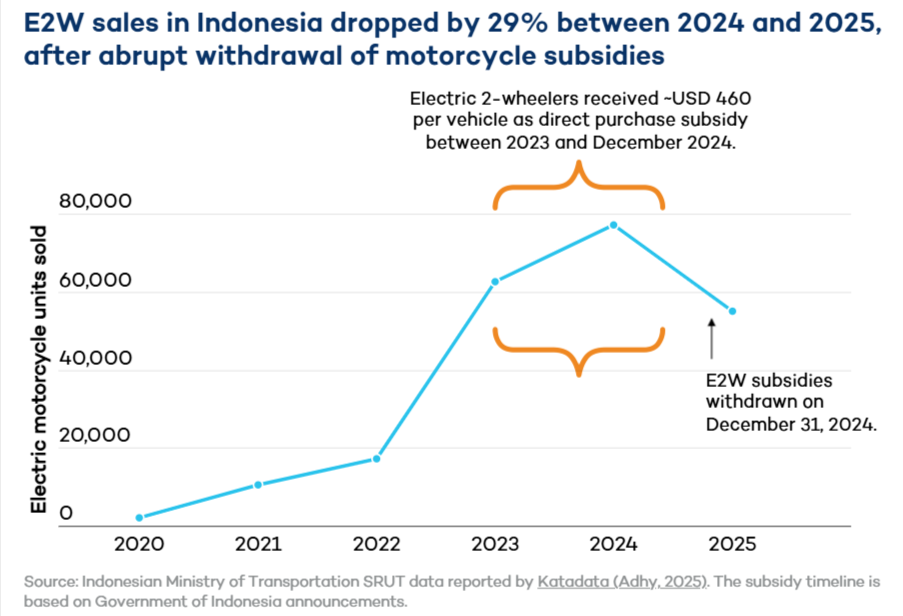
Indonesia provides a useful contrast to India. Both countries have very large two-wheeler markets and used purchase incentives to encourage electrification. In 2023, Indonesia introduced an ~USD 460 subsidy per e-motorcycle for new motorcycle purchases, alongside support for petrol-to-electric conversions. The subsidy was initially limited to people covered by selected social-assistance and small-business programs. Within months, the government widened access: any Indonesian aged 17 or above could qualify, with one subsidized motorcycle allowed per person.
The market responded quickly. Subsidized e-motorcycle purchases rose from 11,532 in 2023 to around 60,000 in 2024, while total E2W sales reached more than 77,000 that year. But the momentum did not last. When the subsidy was not renewed for 2025, e-motorcycle sales fell by 29% to about 55,000 in 2025, reversing part of the previous year’s growth (see the figure below).
Indonesia has since moved to restore support. In August 2026, the government announced a subsidy of about ~USD 173 per e-motorcycle for up to 1 million locally manufactured units. The new program links consumer support to domestic manufacturing capacity, highlighting the importance of strengthening both demand and supply.
Other BRICS+ Approaches to Widening Access
Thailand: Linking Subsidies to Domestic Production
Thailand’s EV 3.0 and EV 3.5 packages (2022 and 2024, respectively) combined market development with support for e-motorcycles. EV 3.5 offers ~USD 155–309 for eligible E2Ws priced below ~USD 4,500 and links consumer support to domestic production. Together, the programs subsidized ~34,500 e-motorcycles while attracting substantial supply-chain investment, illustrating how consumer incentives can sit alongside industrial policy.
China: Using Trade-ins to Support an Affordable Mode
China supports e-bicycle replacement through its national trade-in program, launched in 2024 and extended in 2025. It provides a point-of-sale subsidy to consumers replacing older e-bicycles with new models. The program supported the purchase of 12.5 million e-bicycles in 2025 alone. Rather than limiting eligibility by income, it directs support toward a relatively affordable vehicle used at large scale (as highlighted above).
Malaysia: Using Income Limits to Target Support
Malaysia’s MARiiCAS program combined vehicle and income targeting. Introduced in 2024 and extended through 2025, the program offered a ~USD 600 rebate for purchasing a locally assembled e-motorcycle. Eligibility is restricted to Malaysians earning below ~USD 30,000 annually. By October 2025, 10,600 people had purchased e-motorcycles through this program (87% of its target of 12,155 beneficiaries). This makes Malaysia a useful example of combining support for a widely used vehicle with a clear income limit and a measurable beneficiary target.
The cases presented above in Pathway 1 show that governments can widen EV support by lowering the cost of widely used vehicles, targeting particular users, or maintaining incentives as markets develop.
Pathway 2: Direct Support to Public and Shared Transportation
For people who rely on buses, three-wheelers, and other shared transportation, public support reaches users through services rather than ownership. Financing needs also differ: cities and operators must manage higher upfront EV costs while keeping services financially viable. Brazil and India show how public finance can support buses; China shows what sustained support can achieve at scale; South Africa highlights the financing needs of a largely privately operated transport system; and Ethiopia illustrates an emerging transition.
Brazil: Using Public Finance to Scale up E-Buses
In Brazil, public transport is especially important for lower-income users: in São Paulo, around one third of bus passengers live in households earning up to two minimum wages, while in Salvador almost half of public-transport passengers fall within this income group.
Under the New Growth Acceleration Program (Novo PAC) — announced in August 2023 — Brazil allocated USD 1.7 billion to finance 2,296 e-buses across 61 cities. Sales of zero-emission buses rose 160% (from 324 vehicles in 2024 to 522 in 2025). By early 2026, Brazil’s operational fleet was estimated at ~1,500 battery-electric buses across nearly 30 municipalities, still only around 1%–2% of the country’s estimated 107,000-strong public-transport bus fleet.
The potential for expansion is therefore substantial: the Institute for Transportation & Development Policy estimates that more than 14,000 diesel buses could be replaced by 2030 across 21 metropolitan regions containing 41% of Brazil’s population.
India: Supporting Buses and Shared Three-Wheelers
India is using public support to electrify city buses and to expand the bus service. This matters because the country already has a large public-transport gap: the Government of India’s Ministry of Housing and Urban Affairs estimates that cities with populations above 300,000 will need around 155,000 buses by 2029 to meet basic service levels and currently face a shortfall of ~47%.
The National Electric Bus Programme, launched in 2022, uses large-scale pooled procurement to bring down the cost of e-buses, with an ambition to aggregate demand for up to 50,000 buses. PM-eBus Sewa builds on this by supporting the deployment of nearly 10,000 e-buses across 115 cities. The national government helps cities and pays for essential charging and electricity infrastructure. Importantly, the program gives priority to cities without established bus systems, allowing electrification to expand access to public transport, as well as replace conventional buses.
By July 2026, contracts had been awarded for 5,647 buses across 79 cities, while operating agreements had been signed for 4,330 buses across 53 cities. PM E-DRIVE further complements these efforts, with support planned for up to 14,028 e-buses. These initiatives could help e-buses account for ~30% of medium- and heavy-bus sales by 2029/2030, up from about 7% currently.India also uses PM E-DRIVE to support smaller commercial vehicles, including e-rickshaws, e-carts, and larger E3Ws, used for passenger and goods services. Only commercially registered vehicles are eligible, directing support toward vehicles that provide mobility, delivery services, and livelihoods. By July 2026, the scheme had incentivized ~266,000 E3Ws, against an overall program target of ~328,000.
Other BRICS+ Approaches to Public and Shared Transport
China: Scaling E-Buses Through Sustained Public Support
China began its large-scale push for EVs in 2009 through the Ten Cities, Thousand Vehicles pilot. The program initially subsidized pilots in 10 cities, each aiming to deploy at least 1,000 new-energy vehicles, with early efforts focused largely on public fleets such as buses and taxis.
The city of Shenzhen became an important example, where in addition to the national subsidies, it also provided city-level subsidies (which together covered more than 60% of the purchase cost of e-buses between 2015 and 2017) with new financing arrangements (including leasing) that significantly reduced the amount bus operators had to pay upfront. Charging infrastructure received separate public support, including subsidies for charging stations and easier access to land.
The program later expanded to many cities, which adapted national support through local subsidies, leasing, and lower-cost charging. Shenzhen stands out: these measures helped it become the first city in the world to fully electrify its bus fleet by 2017. By the end of 2024, China had 544,000 new-energy public buses, more than 80% of all urban public buses. The distributional reach of bus electrification is also visible in who uses these services: a Beijing study found that 79% of bus passengers were from low- or lower-middle-income groups.
Ethiopia: Starting the Shift to Electric Public Transport
Ethiopia is at an earlier stage of public-transport electrification. Addis Ababa introduced 100 e-buses in April 2025, adding to a public bus system that, at the time, had 1,170 buses serving residents each day. The country’s 2025–2030 e-mobility strategy targets 4,855 e-buses, and provides support for public charging investment and lease financing through the Development Bank of Ethiopia.
This rollout forms part of a wider market transition: since January 2024, Ethiopia has prohibited imports of gasoline- and diesel-powered vehicles to accelerate e-mobility and reduce spending on imported fuel.
Related Articles
Here is a list of articles selected by our Editorial Board that have gained significant interest from the public:
South Africa: Making Electric Minibusses Work for Small Operators
South Africa presents a different challenge because much public transport is privately operated. Minibus taxis (MBTs) are critical, with around 61.8% of households using them as their main mode of transportation. The network is decentralized and privately owned, with small operators often owning individual vehicles or small fleets. This makes the economics of electrification particularly important: vehicles need to remain productive while operators manage higher upfront costs. MBTs typically operate 9 hours a day and travel 200 km–300 km, making access to charging — and the ability to charge during periods when vehicles are not carrying passengers — particularly important.
A 2026 Cape Town study found that imported e-MBTs can cost 1.4–2 times as much as diesel-based models, and removing import duties would narrow this to 1.2–1.7 times. Yet their lower running costs can offset the higher purchase price. Under lower-cost charging, operating costs were estimated at USD 0.14–0.15/km, compared with USD 0.24/km for diesel. At expensive public chargers, however, the electric cost rose to USD 0.24/km, almost wiping out the savings.
South Africa therefore shows why electrifying shared transport may require more than a cheaper vehicle. Affordable finance can help small operators manage the higher purchase price, while charging needs to fit their routes and working hours so that lower running costs translate into real savings.
The cases presented in Pathway 2 show that electrifying public and shared transport requires different solutions from subsidizing a privately owned vehicle (Pathway 1). Cities may need public finance to expand bus fleets, while smaller transport businesses may need affordable finance and charging arrangements that allow them to keep vehicles in service and earning revenue.
What the Evidence Offers to the Wider Emerging World
The BRICS+ experience suggests that the next phase of EV policy can place greater emphasis on who benefits from electrification, alongside how quickly it progresses.
Recommendations:
- Prioritize transport segments with the greatest distributional reach: Governments can direct support toward vehicles and services that are widely used by lower- and middle-income people. Depending on the country, this may mean E2Ws, E3Ws, e-buses, minibuses, or other shared transport.
- Choose targeting mechanisms that fit local mobility patterns: Malaysia uses income limits for e-motorcycle rebates; China directs support toward a relatively affordable vehicle category; and bus programs reach passengers through public transport (mostly used by lower-to-middle-income consumers). Governments can combine income criteria, vehicle-price limits, commercial-use requirements, or service-based support, depending on who they intend to reach.
- Maintain policy continuity while adjusting support as markets develop: India and Indonesia illustrate how incentives evolve over time. Support can be recalibrated as markets mature, but clear timelines and predictable implementation help consumers and businesses plan their transition.
- Match financial support to vehicle ownership and use: An individual E2W buyer, a city procuring buses, and a small transport operator face different constraints. Policy instruments should reflect these differences through purchase incentives, pooled procurement, concessional finance, or leasing, which reduce upfront costs and make the transition viable.
These cases also point to a broader measure of progress. Alongside EV sales, governments can track who receives support, which transport segments are electrifying, and whether mobility is becoming more affordable and accessible for intended users. The wider opportunity is to shape transport electrification so that it advances decarbonization, cleaner air, reduced oil dependence, and more affordable, accessible, and equitable mobility. The next test of EV policy is therefore not just how fast countries electrify, but who benefits first.
** **
This article was originally published by the International Institute for Sustainable Development (IISD) and is republished here as part of an editorial collaboration with the IISD. It was authored by Sunil Mani, Godwin Paul Chandra Sekar, and Tara Laan.